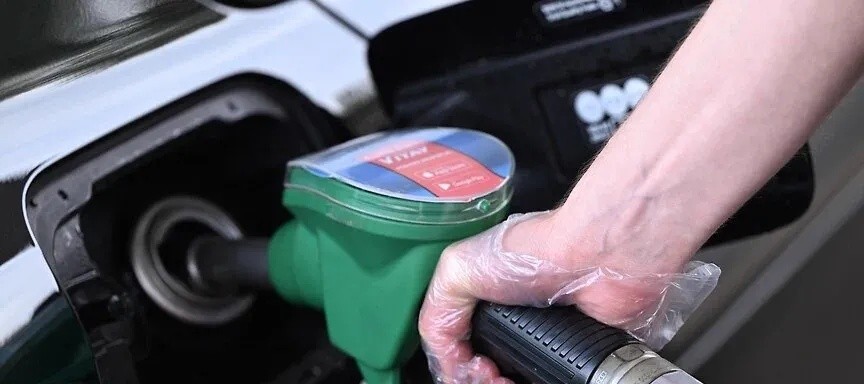
Diesel fuel prices in the United States continue to set record highs, with the average gallon price reaching $6.28 on September 14, 2026, amid expectations of sustained elevated prices in the near term. The American economy relies extensively on diesel
for cargo transportation, agriculture, and construction, and it is also linked to heating fuel. This makes the rise in its prices extend its impact to multiple economic sectors, according to "theconversation". The inflation-adjusted diesel price in late August reached a level
close to that of 2022, with prices continuing to climb. This situation is attributed to three main factors: declining diesel refining capacity, the repercussions of the Russian-Ukrainian conflict, and the American conflict against Iran, which led to the closure of
the Strait of Hormuz to a significant portion of oil and refined product shipments for over six months. Diesel prices surged by 67% in mid-September 2026 compared to their national monthly average in September 2025, when they stood at $3.75 per
gallon. Prior to the initial American-Israeli attack on Iran in late February 2026, the average price in January was $3.52 per gallon, meaning diesel prices have risen by over 78% since the start of the conflict. A contributing factor to
this increase is the years-long decline in the United States' and the world's diesel refining capacity, making it challenging to boost production to compensate for the shortage. Since 2006, the United States began implementing federal regulations requiring refineries to produce diesel
with significantly lower sulfur content than previous levels. This initiative aimed to reduce air pollution and acid rain, particularly those caused by trucks and buses. By 2014, these rules were extended to cover locomotives and marine vessels. The regulations compelled
American refineries to install expensive equipment, a process that took years and cost billions of dollars, while also increasing fuel production costs by 5 to 9 cents per gallon. Low-sulfur fuel also contains slightly less energy per unit volume, necessitating
the use of larger quantities to meet demand. Over the past fifty years, only one refinery has been constructed in Galveston, Texas, with a production capacity of 45,000 barrels per day, which satisfies less than 0.2% of US demand. In 2025,
two refineries ceased operations due to poor economic performance. Furthermore, since 2020, over 12 other refineries have transitioned to producing renewable diesel to capitalize on federal and state biofuel incentives; however, this shift may reduce the actual quantity of fuel
produced by at least half. Consequently, the remaining refineries are operating close to their maximum capacity. Crude oil input to refineries reached approximately 17.5 million barrels per day in late August, with refineries running at about 98% of their maximum capacity,
marking the highest level since 2018. Nevertheless, distillate production, which encompasses diesel, heating oil, and jet fuel, remained below its 2025 levels. Distillate inventories at refineries, distributors, and retailers fell to approximately 103 million barrels by late August, representing the
lowest level for that period of the year since 1951.